
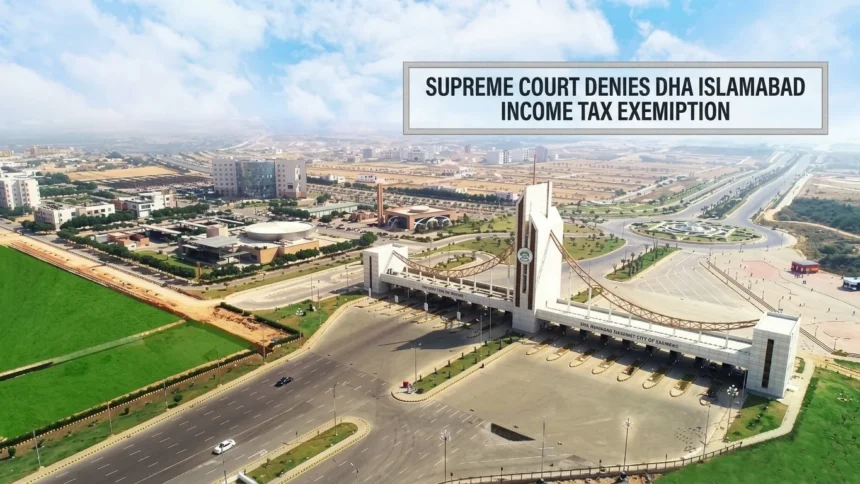
ISLAMABAD: The Supreme Court has dismissed four appeals filed by the Defence Housing Authority (DHA) Islamabad, holding that it does not qualify as a local authority under Section 49(2) of the Income Tax Ordinance, 2001, and is therefore not entitled to claim income tax exemption under the provision.
A three-member bench comprising Chief Justice Yahya Afridi, Justice Naeem Akhter Afghan and Justice Muhammad Shafi Siddiqui announced the judgment on August 17, 2026. Justice Muhammad Shafi Siddiqui authored the verdict.
The appeals had been filed against a January 14, 2019 judgment of the Islamabad High Court, which had rejected DHA’s claim for tax exemption.
The dispute concerned tax years 2005, 2006, 2007 and 2008. DHA had filed its tax returns and claimed exemption under Section 49(2), maintaining that it was a local authority. The returns were initially treated as assessment orders.
However, the Commissioner Audit II and Additional Commissioner Audit II of the Large Taxpayers Unit, Islamabad, later changed the assessments, holding that DHA did not fall within the legal meaning of a local authority and was, therefore, not entitled to the exemption.
DHA had initially succeeded before the Commissioner of Income Tax Appeals, which held that the authority enjoyed the status of a local authority. The Appellate Tribunal Inland Revenue also upheld the decision in January 2012.
The Revenue then approached the Islamabad High Court, which in January 2019 answered the tax references against DHA. DHA subsequently moved the Supreme Court.
Before the apex court, DHA argued that it had been created under law and was responsible for development, planning, regulation and administration of its area. Its counsel contended that DHA exercised public and local powers and that the expression “local authority” should not be interpreted narrowly.
The Revenue opposed the claim, arguing that merely having powers over a defined area or performing public functions did not automatically make an organisation a local authority. It maintained that DHA lacked the essential legal features required for such status.
The Supreme Court observed that the main question was not whether DHA performed public or municipal functions or operated within a defined area. Rather, the issue was whether the law had conferred upon DHA the legal powers and attributes necessary for an organisation to be treated as a local authority under Section 49(2).
The court examined the definition of local authority under the General Clauses Act, 1897, and found that an authority must be legally entitled to, or entrusted by the government with, the control or management of a municipal or local fund.
The bench also considered the Local Authorities Loans Act, 1914, under which a local authority may have legal power to control a local or municipal fund or impose a cess, rate, duty or tax within a local area.
The judgment referred to earlier Supreme Court rulings. In the Ataul Huq case, the court had explained that a local authority normally carries out local government functions and may have powers to frame bylaws, impose taxes and manage a local fund.
In the Thal Development Authority case, the authority was treated as a local authority because the law had granted it wide powers, including the authority to levy taxes and maintain its own fund.
The Supreme Court also relied on principles discussed in Province of Punjab v Market Committee. These included having a separate legal identity, continuing existence, a common seal, the ability to sue and be sued, operating within a defined territory, performing local government functions, making bylaws, imposing fees or taxes, and raising and managing its own fund.
The court held that these features must be substantially and predominantly present for an organisation to qualify as a local authority.
Applying these principles to DHA, the Supreme Court said the material before it only showed that DHA operated within a defined area and performed development, planning, regulation and administrative functions. The court held that this was not sufficient to establish the required legal status.
The bench further found that the record did not show that DHA was legally entitled to control or manage a municipal or local fund, or that it had the legal power to impose a cess, rate, duty or tax within its area.
The court stressed that an organisation does not become a local authority merely because its activities are confined to one area or because it performs public functions. What matters, the judgment said, is the legal character conferred by law and the actual powers granted to the organisation.
The Supreme Court held that DHA had not demonstrated the wider legal powers that supported the status of local authorities in earlier cases.
The apex court, therefore, rejected DHA’s claim that it fell within the expression “local authority” under Section 49(2) of the Income Tax Ordinance, 2001. Consequently, the income tax exemption claimed by DHA was held to be unavailable and all four appeals were dismissed.